TL;DR
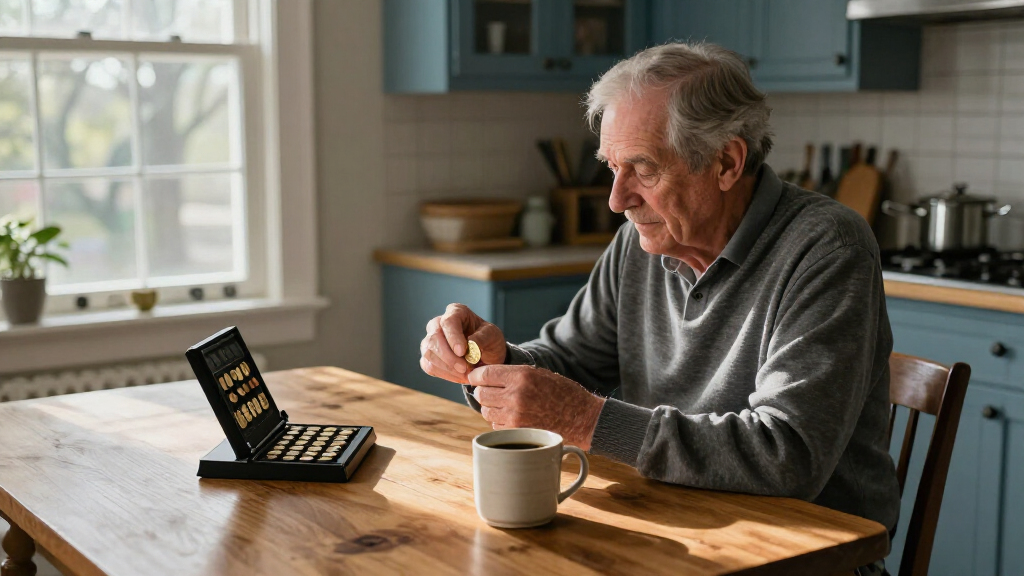
A 70-year-old retired banking vice president in Bexley, Ohio, told Kiplinger that he reached $1 million in his mid-30s after beginning to invest as a teenager and living below his means. He and his wife continued investing and are now multimillionaires, according to his account; the profile does not provide a detailed breakdown of their assets or returns.
A 70-year-old retired banking vice president in Bexley, Ohio, says he reached his first $1 million in his mid-30s after starting to invest at 18, saving regularly and keeping household spending below his income. In a Kiplinger “My First $1 Million” profile, he said he and his wife continued investing and are now multimillionaires, though the publication did not provide an independently verified account statement or a detailed calculation of their wealth.

Get home office essentials delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
The man told Kiplinger that he began with $25 a month in a mutual fund at age 18, then bought individual stocks. At 20, while working on the night stock crew for a national food chain, he said he began putting $50 a week into the company’s stock. He had worked from age 15, starting at a small pizza restaurant for $1.35 an hour, according to the interview.
After 12 years in the grocery business, he moved to the company credit union, taking a pay cut, he said. By then, he had accumulated more than 10,000 shares of his former employer’s stock and had started buying other equities. He attributed reaching his million-dollar goal ahead of his target age of 40 to regular investing and compounding, alongside spending less than the household earned.
The profile identifies him as married and retired, and reports a $95,000 salary. His wife worked at the same food chain and later retired after 45 years as a certified public accountant, according to the account. He said he retired at 64 after his employer repeatedly asked him to stay for another year; he had initially expected to stop working closer to 60.
How His Saving Plan Built Wealth
The account illustrates how a long investing timeline can matter: the interviewee says he started with modest contributions as a teenager, kept investing through different jobs and continued after his first million. His experience may offer readers a concrete example of the role that regular contributions, time in the market and controlled spending can play in building assets.
It is a personal account, not evidence that the same approach will produce comparable results for others. The story gives no complete record of investment costs, taxes, market returns, household income over time, or the current value and composition of the couple’s assets. Individual outcomes vary, and investments can lose value. Kiplinger says its profiles are intended to share people’s experiences, not provide financial advice.
Products Worth Considering

Vari ComfortEdge 48×30 Inch Adjustable Electric Standing Desk

Dell 27 Plus S2725HSM 27-Inch FHD 144Hz Monitor with Speakers

Samsung Odyssey G55C 32-Inch QHD Curved Gaming Monitor
As an affiliate, we earn on qualifying purchases.
From Teen Investor to Retiree
The subject said his interest began when he was about 10, after conversations with an aunt who had invested in stocks. Her family had started a business in the 1920s, he told Kiplinger. He later read publications including The Wall Street Journal, Barron’s and The Kiplinger Letter, along with books such as The Millionaire Next Door.
He said he managed his investments himself and did not work with a financial adviser, describing research and investing as a hobby. In retrospect, he said he might have contributed to a Roth IRA earlier. He also told Kiplinger that his first million did not change his lifestyle much: he and his wife continued to use coupons and sale prices, drove cars from 2008 and 2011, and lived below their means. He said they now travel more often and give more to others.
“When I was 18, I laid out a plan to have $1 million by the time I reached 40.”
— The retired banking vice president, speaking to Kiplinger
What the Profile Does Not Show
Kiplinger’s article is based on an anonymous subject’s answers, and the outlet says participants in the series are not identified to readers. The material provided does not include documents confirming the couple’s net worth, the date their investments first reached $1 million, or how the publication defines that milestone. It also does not clarify whether the figure refers to investable assets, total assets, or net worth after liabilities.
The interviewee’s reported salary is one figure, not a full account of household earnings across his career. The profile also gives no portfolio allocation, investment performance history, tax treatment, or contribution totals beyond the examples he shared. The extent to which his outcome depended on company-stock performance, broader market gains, or other factors is not established.
The Couple Continues Investing
The retiree said he and his wife plan to keep investing and continue their current approach to spending. He also said they have been traveling more and giving more in retirement. Kiplinger’s profile does not announce a specific next financial milestone, planned portfolio change, or follow-up interview date.
For readers, the next step is not a guaranteed result but a personal assessment of savings, time horizon, risk tolerance and retirement needs. The interviewee said he would advise others to be consistent, but his experience is not a forecast of what another investor will earn. The publication’s series presents individual stories rather than personalized recommendations.
Key Questions
How did the retired Ohio executive say he made his first $1 million?
He told Kiplinger that he began investing at 18, started with $25 a month in a mutual fund, later bought individual stocks and invested $50 a week in his employer’s stock while working in a grocery business. He said regular investing and living below his means helped him reach the goal.
When did he say he reached $1 million?
He said he was in his mid-30s when he reached the milestone, about 35 years before the profile, and that he did so ahead of his original target of age 40. The article does not give a precise date.
What does the profile say about his household’s wealth now?
The interviewee said he and his wife are now multimillionaires. The profile does not provide documents or a detailed account of their assets, liabilities or net worth.
Did he use a financial adviser?
No. He told Kiplinger that he handled his own investments and research, which he described as a hobby. That was his personal choice and does not establish that self-management is suitable for every investor.
Is this profile financial advice?
No. Kiplinger describes the series as a way to share individual experiences, not financial advice. Investment returns are uncertain, and investors can lose money; this profile does not guarantee similar results for others.
Source: kiplinger.com